

Cash Advance: Get 250 Fast

- 984.00 Reviews
- 4.7
- Downloads
- 100,000+
Our take on Cash Advance: Get 250 Fast from Appgk
When an unexpected bill lands between paydays, the appeal of Cash Advance: Get 250 Fast is easy to understand. It presents itself as a finance app built around a short, direct borrowing journey rather than a large budgeting suite. I approached it as a tool for a specific moment: checking whether a cash advance can help with a temporary gap, while remembering that any borrowing decision deserves more care than the word “fast” might suggest.
The app is free to install, carries an Everyone age rating, and is published by KOMPANIIA LORENS PP. Its public reception is encouraging, with a 4.7 average from around 25 thousand ratings and close to a thousand written reviews. That does not make every borrowing outcome suitable for every person, but it does suggest that many users find the basic experience approachable.
What the app feels like to use when time matters
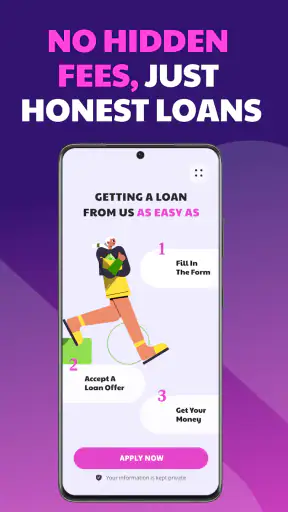
My first impression is that the product is designed to reduce hesitation. The store positioning focuses on a short application path and no subscription fees, so the experience is easier to understand than a finance app that mixes loans with investing, credit monitoring, bill negotiation, and account management. If your immediate question is simply whether you can request a cash advance, this narrow focus is useful.
That simplicity should not be confused with guaranteed instant money. A quick application is only one part of the process. Eligibility, identity checks, account details, repayment terms, and the eventual transfer can all affect how quickly the money becomes useful. I would treat the app as a way to begin reviewing an option, not as a promise that an emergency expense will be solved immediately.
Best Parts of Cash Advance: Get 250 Fast
Things to Keep in Mind About Cash Advance: Get 250 Fast
The most sensible workflow is to open it before you are under maximum pressure. Read every screen, check the total repayment obligation, and make sure the repayment date fits your next income cycle. Doing those steps calmly is a practical advantage: it prevents the urgency of a late utility bill or a necessary purchase from turning into an automatic acceptance.
One detail I appreciate is the absence of a subscription fee in the app’s positioning. For someone who only needs to investigate a short-term advance, avoiding a recurring membership charge matters. Still, “no subscription fees” does not mean borrowing is cost-free. Any available fee, interest, or repayment condition should be considered separately, and the final offer is more important than the download price.
News and Features Related to Cash Advance: Get 250 Fast

News
YouTube Turns a Quick Video Check Into an Hour of Watching

News
BeautyPlus Makes Portrait Retouching Feel Like Your Own

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
In an everyday scenario, imagine a necessary car repair arriving a few days before payday. I would use the app to see whether the requested amount and repayment schedule are realistic, then compare that result with asking the repair shop about a payment arrangement, using an existing emergency fund, or postponing a nonessential purchase. The app can be useful in that comparison, but it should not replace the comparison.
Where the short application approach helps
A focused design can be less tiring than a traditional bank application. You are not entering an app intended to manage your entire financial life; you are looking at a cash-advance product. That makes it easier to keep the purpose in view and finish the process without wandering through unrelated tools.
Don't want to read the full review?
It is also a reasonable fit for people who want to review an option from a phone instead of visiting a branch. The current release is version 1.2.2, and the app has passed the early stage of a brand-new launch, having been released in July 2023. Its install base is over one hundred thousand, which gives the product some practical visibility without making it a universal solution.
My advice is to prepare before starting. Know how much you actually need, when your next dependable income arrives, and what amount you can repay without creating a second shortfall. This small preparation is one of the best ways to make a fast finance workflow safer. Requesting the maximum simply because it appears available can turn a temporary bridge into a longer and more expensive problem.
Screenshots
What happens during heavier moments
The demanding moment for this app is not entertainment-style heavy use. It is the point at which many people open it while worried, distracted, and trying to finish a financial task quickly. A stable interface and clear sequence matter more here than decorative extras. I found the focused purpose helpful because there are fewer unrelated decisions competing for attention.
Even so, financial applications require a slower reading habit than their compact design may encourage. A user may be tempted to tap through each step simply to reach an answer. I would pause at every stage involving personal information, eligibility, repayment, or authorization. The fastest safe workflow is not the one with the fewest seconds on screen; it is the one that avoids a rushed commitment.
Another realistic heavy-use case is comparing several options in one evening. Someone facing an urgent expense may check this app, a bank’s overdraft facility, a credit-card cash option, and a local lender. In that situation, keep a written note of the total amount to repay and the due date for each choice. A clean comparison is more reliable than remembering a series of attractive headline figures.
The app’s narrow scope is an advantage during this kind of review, but it is also a limitation. It is not the place I would go for a complete spending plan, long-term debt reduction, investment guidance, or a detailed savings system. A dedicated budgeting app or a conversation with a bank may be better when the underlying issue is recurring rather than temporary.
Reliability means more than a good rating
The 4.7 average and strong volume of ratings make a positive first signal. They indicate that the app has earned broad approval from people who chose to rate it. I would still avoid treating ratings as proof that every applicant receives the same result. Finance products depend on individual circumstances, and satisfaction with the interface is not the same as suitability of a loan.
For reliability, I look for consistency in the basic journey: can I understand what is being requested, review the important terms, and return to the process without confusion? A focused cash-advance app has a natural advantage here because it does not need to support a large collection of unrelated financial features. That can make the path easier to follow than a general-purpose banking application.
There is also a reliability question around expectations. The name emphasizes speed and a specific cash figure, but I would not interpret that as a universal approval or a guaranteed delivery time. A responsible user should allow room for verification and processing rather than planning an essential payment around money that has not yet arrived.
If an application pauses or an attempt does not complete, the best recovery is to avoid repeatedly submitting requests without understanding the status. Check whether the previous attempt appears to have finished, review any confirmation information, and contact the appropriate support route shown inside the product if clarification is needed. Repeated taps can create uncertainty about whether more than one request was recorded.
That recovery mindset is particularly important with borrowing apps. A failed music download is inconvenient; an unclear financial submission can have consequences. I would take screenshots or keep personal notes of confirmation details where appropriate, while avoiding the storage or sharing of sensitive information in unsafe places. The app should be treated as a financial workflow, not as a casual form.
Device and operating-system considerations
The minimum operating-system requirement is Android 7.0, so the app is accessible to people using many older Android phones as well as newer devices. That is helpful for users who do not upgrade frequently. At the same time, an older phone can introduce its own issues: limited free storage, an outdated system, weak connectivity, or aggressive battery management may make any online finance task less comfortable.
I would use a dependable connection and enough battery before beginning. This is not because the app is known to demand unusual resources, but because interruptions are especially unwelcome when entering financial details. If the device is nearly full or frequently closes background applications, clear those problems first rather than assuming the app itself is at fault.
The app is free to download, which lowers the barrier to trying the initial experience. The more important device constraint is privacy. Use a personal phone with a screen lock, avoid public Wi-Fi when possible, and do not hand the device to someone else while an application or confirmation screen is open. These habits are more valuable than chasing a slightly newer handset.
I would also keep the operating system and the app updated through the official store. The current version is 1.2.2, and staying current is a sensible way to receive the developer’s latest compatibility and stability work. If the app behaves strangely after an interruption, restarting the phone and reopening the process is a safer first step than repeatedly entering the same information.
People using iPhones should pay attention to the platform available in their region before planning around it. The product information identifies the app as a mobile finance offering, but the practical experience depends on the store, device, and availability presented when you search. I would confirm that the correct version is available on your own device before an emergency occurs.
Who will benefit, and who should choose another route?
I see the strongest fit for an adult who needs to examine a short-term cash option, understands the difference between borrowing and free money, and can identify a credible repayment source. The Everyone rating makes the app broadly classified for general audiences, but the financial decision itself is still an adult responsibility. A simple interface does not remove the need to understand the obligation.
It is less suitable for someone whose income is already committed, whose expenses regularly exceed earnings, or who would need one advance to repay another. In those cases, the central problem is not a single timing gap. A debt adviser, bank conversation, employer advance, or carefully planned expense reduction may offer a healthier path than another short-term commitment.
I would also skip it when the amount needed is uncertain. Borrowing a little extra “just in case” can make repayment harder, while borrowing too little may leave the original problem unresolved. Work out the exact essential cost first. If the app presents an amount that does not match that need, do not force the situation to fit the product.
Compared with a conventional bank, this app may feel more direct and less cluttered, especially when the goal is to investigate a cash advance rather than manage an account. A bank may be preferable when you already have an established overdraft, a personal-loan relationship, clearer support, or a lower-cost alternative. Compared with a budgeting app, this product addresses access to funds rather than the habits that prevent future shortfalls. The right choice depends on whether your problem is timing or structure.
One useful trade-off is convenience versus context. A specialized app can get you to a relevant decision faster, but a bank or full financial-management service may show more of your wider situation. I would use this app as one option in a comparison, not as the only financial voice guiding a high-stakes choice.
My performance verdict after looking at the whole experience
From a performance perspective, the strongest quality is focus. The app is built around a single financial purpose, and that should make it easier to approach than a crowded money-management platform. Its broad adoption, high average rating, free installation, and support for Android 7.0 or later all make it approachable for a wide range of phone users.
Its perceived speed is more nuanced. The application journey may be quick to begin, but approval and delivery should never be assumed from the title or the short description. If the expense is urgent, start early, read carefully, and keep a backup plan. That is the practical difference between using a cash-advance app thoughtfully and relying on it as a guaranteed emergency button.
Resource demands do not appear to be the reason to avoid it. The more meaningful constraints are your device’s condition, your connection, your privacy setup, and your ability to repay. A newer phone will not make an unsuitable borrowing decision safer, while a modest phone can be perfectly adequate if it is secure and stable.
My overall view is favorable but deliberately cautious. Cash Advance: Get 250 Fast is worth considering when you need to explore a short-term advance and want a focused mobile route without a subscription fee. I would recommend it to a friend only with one condition: compare the complete repayment commitment with alternatives before accepting anything.
For a one-off timing problem, that approach can make the app genuinely useful. For repeated financial pressure, choose help that addresses the cause rather than repeatedly covering the symptom. Used within those boundaries, this finance app offers a clear starting point; used without them, its convenience could encourage a decision that deserves much more time.
In the end, Cash Advance: Get 250 Fast succeeds best as a quick way to investigate an option, not as a substitute for a budget, emergency fund, or trusted financial advice. I like its focused presentation and accessible entry point, but the final verdict depends less on how quickly the screens open than on whether the repayment fits comfortably into real life.
Cash Advance: Get 250 Fast FAQ
What is Cash Advance: Get 250 Fast, and how does it work?
Cash Advance: Get 250 Fast is a financial app designed to help eligible users explore short-term cash advance options through a mobile application. After creating an account, you may be asked to provide personal, employment, income, and banking details so the service can assess eligibility. Approval, available amounts, fees, and repayment terms are not guaranteed and may depend on the participating lender or provider.
Can I really receive up to $250 immediately after applying?
The app’s name refers to the possibility of accessing an advance of up to $250, but this should not be interpreted as a guaranteed or instant payment. The amount you qualify for depends on your information, eligibility, verification results, and the terms offered by a third-party provider. Even after approval, transfer times may vary by bank, payment method, weekends, and processing requirements.
Are there fees, interest, or repayment requirements?
Before accepting any offer, carefully review the complete cost of borrowing. Depending on the provider, a cash advance may involve subscription charges, service fees, expedited-transfer fees, interest, or other costs. Repayment may be scheduled automatically from your bank account or debit card on a specified date. Never accept an offer until you understand the total repayment amount, due date, and cancellation policy.
What personal information does the app request, and is it safe to use?
A cash advance service may request sensitive information such as your name, address, phone number, employment details, income, identification information, and bank-account data. Install the app only from an official store, check its developer and privacy policy, and confirm why each permission is needed. Avoid entering information through suspicious links, and contact support if you notice unexpected account activity.
Who should avoid using a cash advance app?
Cash advance apps are generally intended for short-term financial needs, not for managing ongoing debt or regular expenses. You should consider avoiding one if you cannot repay the advance on time, already rely on multiple borrowing services, or are uncomfortable sharing financial information. Compare alternatives first, such as speaking with your bank, requesting an employer advance, or contacting a nonprofit financial counselor.











